Address
304 North Cardinal
St. Dorchester Center, MA 02124
Work Hours
Monday to Friday: 7AM - 7PM
Weekend: 10AM - 5PM
Address
304 North Cardinal
St. Dorchester Center, MA 02124
Work Hours
Monday to Friday: 7AM - 7PM
Weekend: 10AM - 5PM
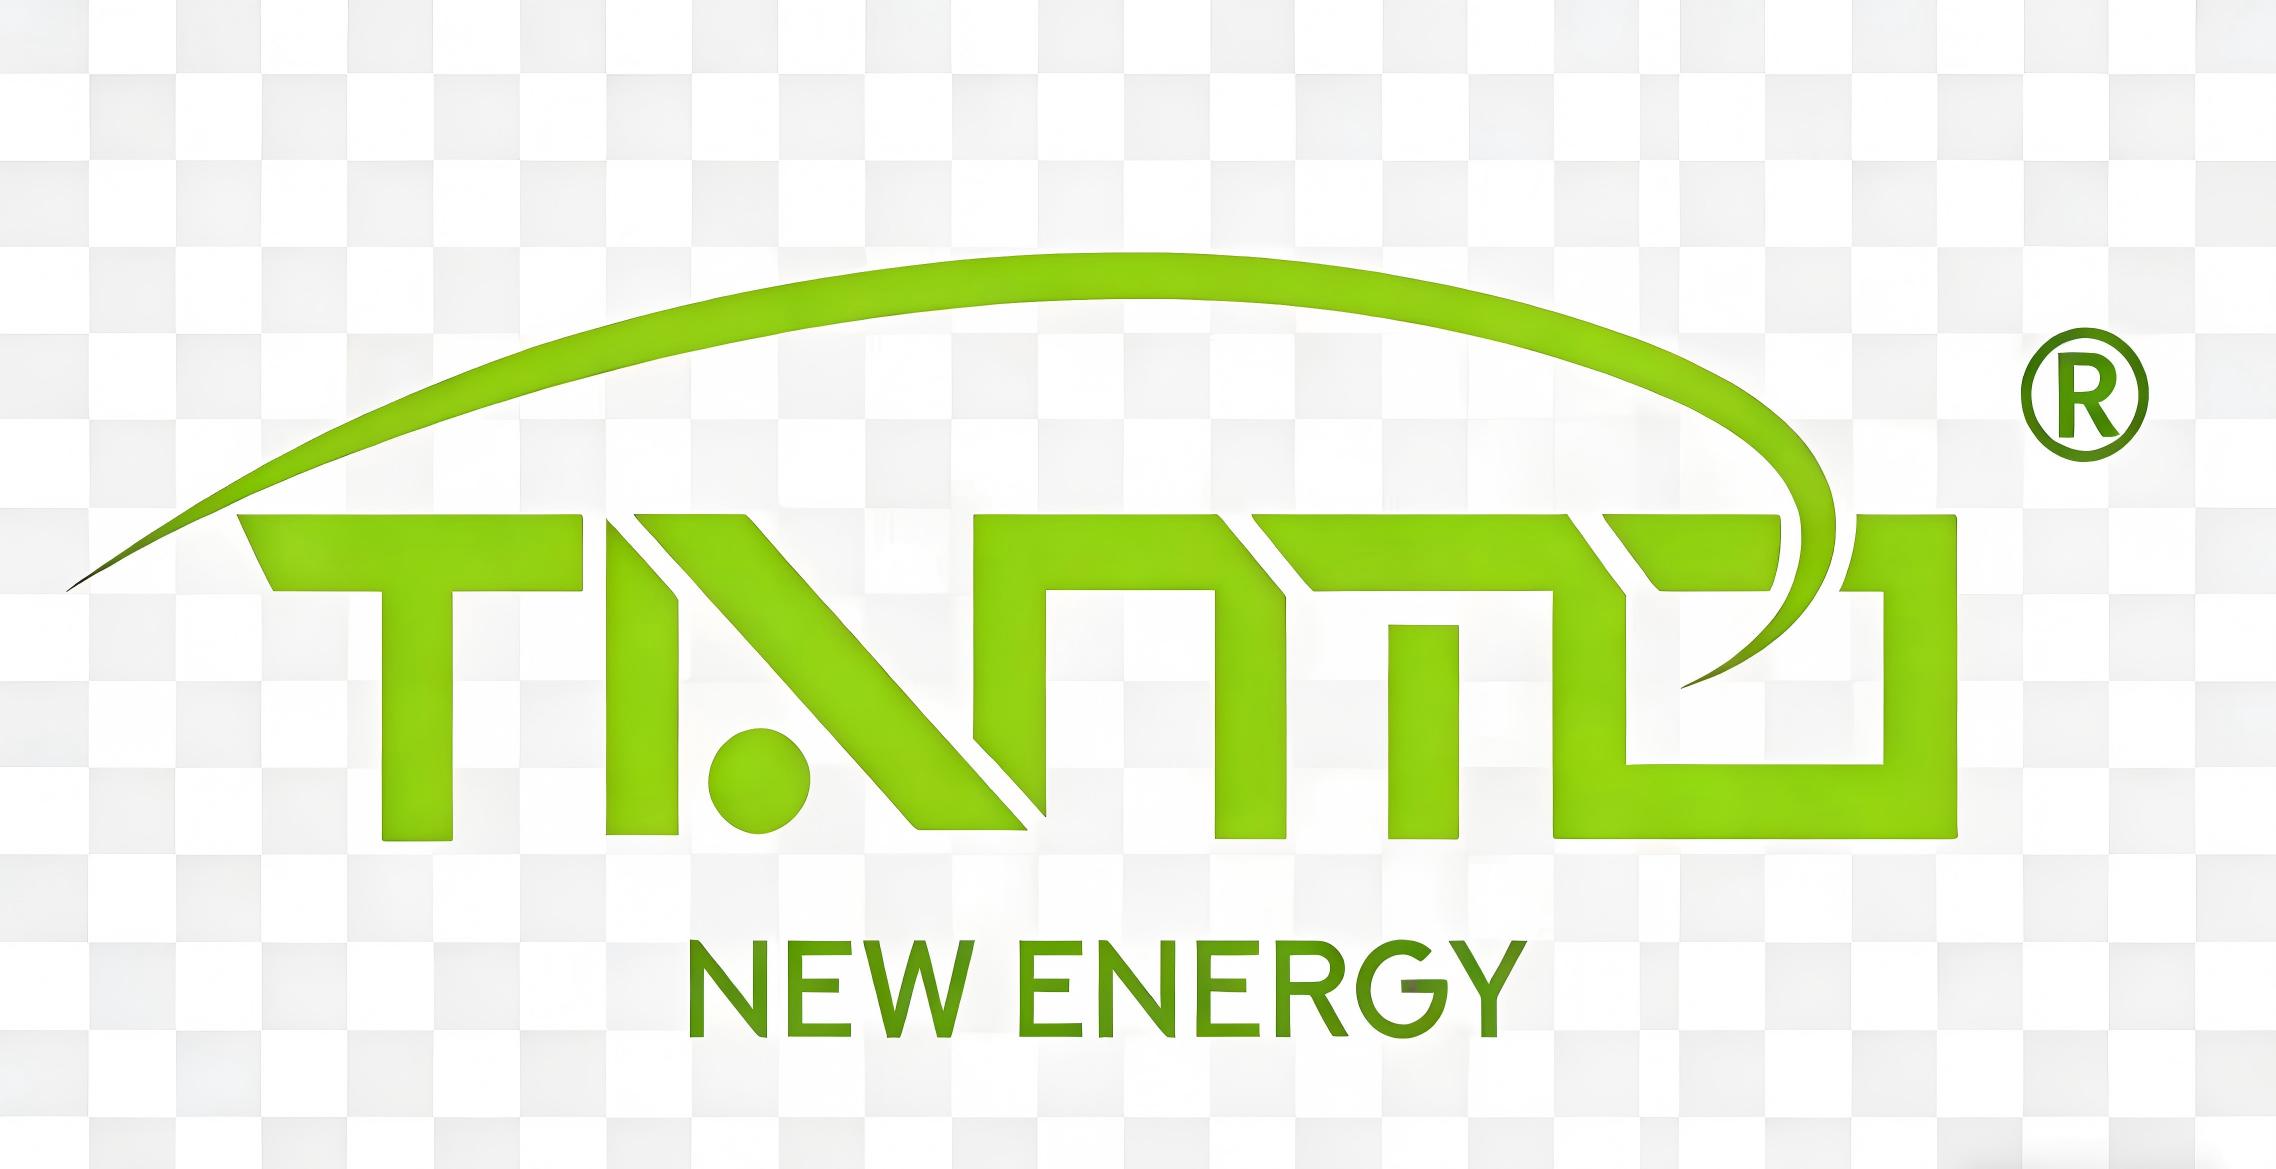
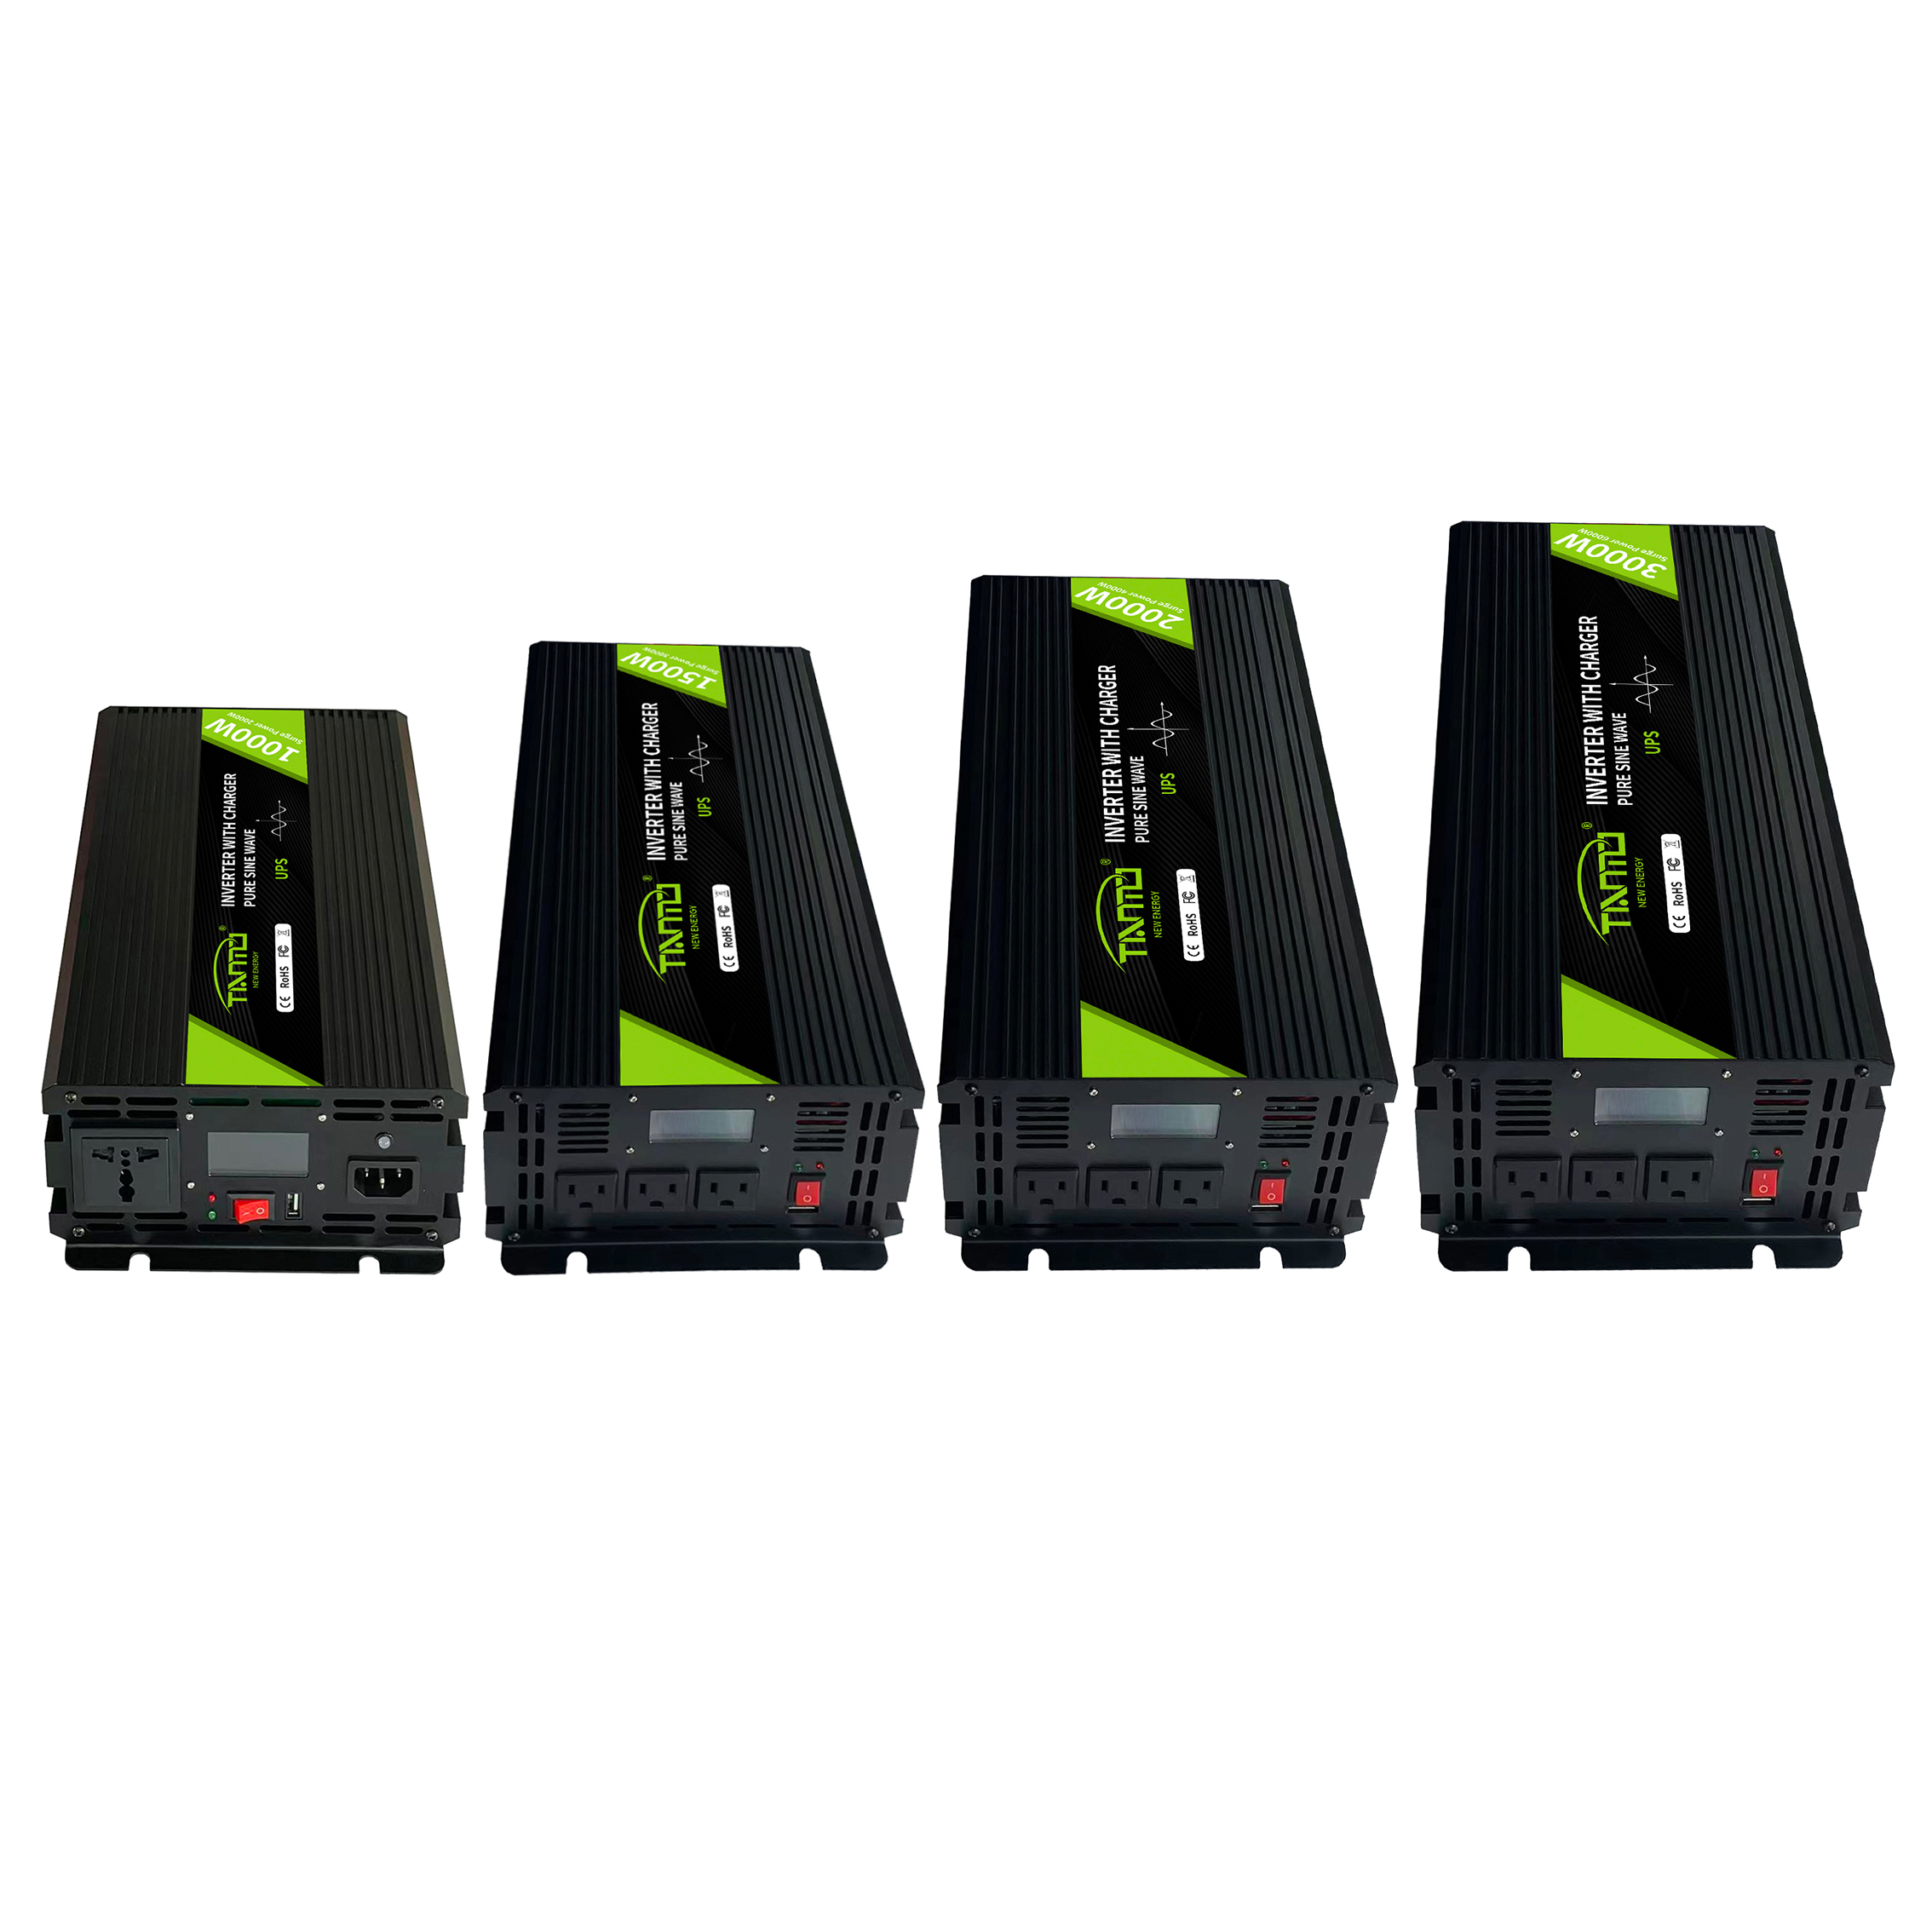
The Solar Inverter at the Crossroads of Geopolitics and Energy Transition
The global energy transition is no longer solely a story of falling solar panel costs or expanding wind farms. At the heart of this transformation lies a critical, yet often overlooked, component: the solar inverter. As the device responsible for converting direct current from solar panels into usable alternating current for the grid, the solar inverter has become far more than a mere technical accessory. In 2026, it has emerged as a focal point of geopolitical tension, technological innovation, and market evolution, reflecting the complex intersection of energy security, industrial policy, and global supply chains.
The most striking development in the solar inverter sector this year has been the escalating wave of trade restrictions from Western governments. In August 2026, the United States signed an executive order declaring a national emergency and banning the use of certain foreign-made power equipment, including specific solar inverter models and battery storage systems, in the U.S. power grid. This followed an earlier move by the Federal Communications Commission (FCC) in July, which placed overseas-produced grid-tied inverters on a “covered equipment list,” effectively barring their import and sale. The stated rationale is national security, with officials expressing concerns that these smart devices could be exploited to disrupt critical infrastructure during a crisis.
This American stance is not an isolated incident but part of a broader transatlantic alignment. Earlier in 2026, the European Union formally designated China as a “high-risk country” for cybersecurity, prohibiting public-funded renewable energy projects from using solar inverter and energy storage products from China, Russia, Iran, and North Korea. The EU’s measure, which took effect on May 1st, targets the financial lifeline of many projects, cutting off access to subsidies from institutions like the European Investment Bank. This policy is projected to impact approximately 14% of European solar demand through 2030. While Western governments frame these actions as necessary security precautions, they are widely perceived in Beijing as politicized and discriminatory, a form of “stigmatization” that violates market principles and threatens global supply chain stability.
The irony of these bans is palpable when confronted with market realities. Despite the political rhetoric, the world remains deeply dependent on Chinese manufacturing for this critical technology. China accounts for roughly 80% of global battery and solar inverter production capacity. In 2024, Chinese manufacturers shipped 330 GW of inverters, representing 56% of the global total. In stark contrast, domestic U.S. manufacturers can only meet about 7% of American demand. The U.S. grid currently relies on inverters for approximately 46 GW of power. Attempting to decouple from the dominant supplier in such a short timeframe is less a security strategy and more a forced disruption that will inevitably lead to higher costs and project delays, a bill that will ultimately be paid by Western consumers and taxpayers.
However, the narrative of the solar inverter is not defined solely by trade wars. Beneath the geopolitical friction lies a powerful story of technological advancement and market diversification. The industry is undergoing a profound transformation, shifting from a simple hardware supplier to a provider of intelligent energy solutions. The integration of Silicon Carbide (SiC) semiconductors is becoming standard, significantly boosting efficiency and power density. Furthermore, the rise of “grid-forming” inverters is a game-changer. Unlike traditional grid-following models, these advanced solar inverter systems can actively stabilize voltage and frequency, providing essential inertia to grids increasingly dominated by variable renewable energy. This technology is already seeing large-scale deployment in places like the UK and is becoming a mandatory requirement in regions like Xinjiang, China.
Simultaneously, the demand landscape is shifting dramatically. The explosive growth of AI data centers has created a new, massive application for energy storage and stable power, directly driving demand for high-capacity solar inverter and storage systems. In China, new national standards are forcing a wave of upgrades, mandating that older, non-compliant inverters be replaced to meet stricter grid-interconnection requirements. This domestic policy is creating a robust replacement market independent of export dynamics.
Moreover, Chinese manufacturers are successfully navigating the geopolitical headwinds by diversifying their export markets. While North American and some European channels face restrictions, other regions are experiencing a boom. Exports to Australia, the Middle East, Africa, and Latin America have surged, with some markets seeing growth rates exceeding 100%. The global nature of the energy transition ensures that demand is not monolithic; when one market erects barriers, others open up, driven by local needs for energy security and decarbonization.
In conclusion, the solar inverter has become a microcosm of the broader challenges facing the global energy transition. It is a technology caught between the urgent need for decarbonization and the rising tide of geopolitical rivalry. While protectionist policies may offer short-term political capital, they cannot erase the fundamental realities of industrial scale, technological leadership, and global market demand. The long-term trajectory will be determined not by executive orders, but by the relentless pace of innovation and the universal imperative for reliable, affordable, and clean energy. The future of the solar inverter will be shaped by those who can best navigate this complex landscape, balancing security concerns with the practical necessities of building a sustainable power grid for the 21st century.